- Entering text into the form field will trigger a list of options
Trending Searches
- Invest / Login

Q2 FY27 Earnings: Profit Growth Continues to Pick Up and Broaden

Last Updated On: 17 Nov 2026
5 min read
What’s the Point?
- Amid a challenging geopolitical environment, corporate profitability has continued to recover, with Nifty 500 net profit growing 29% YoY (Year on Year) in Q2FY27, up from 12% in Q1FY27 and the healthiest growth in 12 quarters. Excluding oil and gas, profit grew 24%.
- Broad-based earnings growth across market caps (excluding oil and gas): large caps grew 26% YoY, mid caps 21% YoY and small caps 22% YoY.
- Growth was well distributed, with 17 out of 22 sectors delivering double-digit YoY profit growth and only 3 sectors declining.
Q2FY27 corporate earnings came in strong, with Nifty 500 companies posting 29% YoY profit growth , more than double the 12% reported in Q1FY27, on revenue growth of 23%. Growth was led by metals and mining (88% YoY) and oil and gas (61% YoY). Excluding oil and gas, profit growth for Nifty 500 was 24% , a similar pace to Q1FY27.
Broad-Based Earnings Growth
Earnings growth was broad-based. Around 75% of Nifty 500 companies grew profit and around 57% grew it by 10% or more, with 17 sectors out of 22 reporting double-digit YoY growth , 2 single-digit and 3 declining. Financials, the largest profit pool in the index, contributed across segments: banks 20% YoY, other financials 20% YoY and insurance 17% YoY. Oil and gas, a drag in Q1FY27, was the largest contributor to the increase this quarter, as upstream producers, integrated refiners and one state-run fuel retailer posted sharp gains.
Across market-cap segments, large caps grew 32% YoY and small caps 31%, while mid caps grew 20%, a recovery from 4% in Q1FY27. Excluding oil and gas, the three segments grew at a similar pace: large caps 26% YoY, mid caps 21% YoY and small caps 22% YoY.
On the margin front, aggregate EBITDA (Earnings before interest, tax, depreciation, amortisation) of companies outside financials grew 28% YoY , ahead of their revenue growth of 26%, and the margin improved to 17.0% from 16.7%. Excluding oil and gas as well, the margin was steady at 18.5%, so profit growth there came from higher revenue at stable margins.
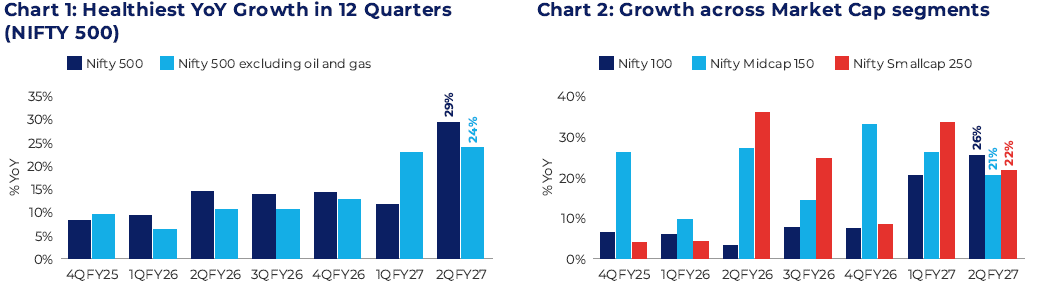
Source: Kotak Institutional Equities, Capitaline. Chart 1: Nifty 500 profit growth (% YoY), all companies and excluding oil and gas. Chart 2: Profit growth by market-cap segment excluding oil and gas (% YoY).
Sectoral Snapshot
- Oil & Gas: The largest contributor to the quarter's profit growth. Refining margins widened sharply as disruption to refining capacity in West Asia and Russia tightened global fuel supply, and upstream producers gained on higher crude realisations. State-run fuel retailers returned to profit after losses in the previous quarter, though elevated crude prices kept their fuel marketing margins under pressure.
- Banks: Profit growth was driven by lower credit costs, with asset quality improving further. Strong deposit mobilisation, including foreign currency (FCNR) deposits, has strengthened the funding base for continued loan growth.
- Metals & Mining: Among the largest gains in the index. Higher metal prices lifted realisations well ahead of volumes, and strong production along with a recovery in overseas aluminium operations added to profit.
- Power: Profit grew strongly on higher power demand and generation. Part of the increase came from one-off items, including prior-period revenue recognised during the quarter.
- Information Technology: Reported growth was supported by translation at a weaker rupee, while constant-currency growth stayed modest. Good growth of revenue from AI-led services and better hiring compared to the recent past were the bright spots.
- Automobiles & Components: Volumes were strong against a base that preceded the GST rate cuts, with two-wheelers and exports leading. Higher commodity costs linked to the West Asia conflict weighed on margins, particularly for passenger vehicle makers.
- Capital Goods: Order inflows were healthy and revenue grew well. Higher commodity costs and slower execution in some engineering and construction projects kept profitability from keeping pace.
- Consumption: Discretionary segments such as consumer durables and consumer services posted strong profit growth. Consumer staples saw healthy volumes, while higher palm oil and crude-linked input costs narrowed margins, with price increases recovering a part of the impact.
- Healthcare: For healthcare services, companies grew in line with or slightly below par, depending on capacity build-up. For pharma, CDMO companies grew in double digits, while generic pharma companies displayed divergence in their growth profile.
- Construction Materials: Volumes grew, while higher petcoke, coal and diesel costs narrowed margins. Cost pressures may increase before softening in early FY28. The industry is attempting price hikes, which may cushion the impact.
Conclusion
After relatively sluggish growth in the last couple of years, Nifty 50 earnings have regained momentum. Valuations have moderated meanwhile, with the Nifty 50 trading at 18.7x oneyear forward earnings as of November 16, 2026, against its 10- year average of 18.8x.
With earnings momentum recovering and valuations having moderated from expensive levels, the long-term view on the equity market remains relatively constructive.
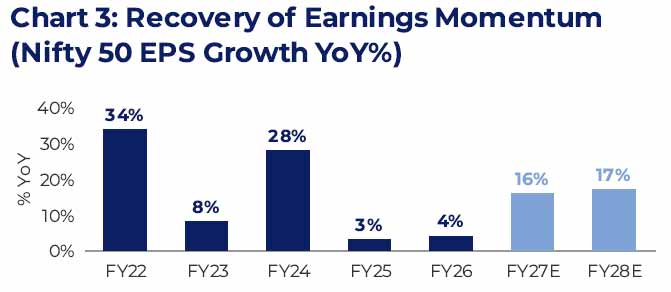
Source: ICICI Securities. Nifty 50 EPS growth (% YoY); FY27E and FY28E are estimates.
Sources: Kotak Institutional Equities, ICICI Securities, Capitaline, Bloomberg, ICRA and other publicly available information.
About Tuesday’s Talking Point (TTP): TTP is an effort by HDFC AMC to guide key conversations in the Indian financial markets and investing ecosystem. We aspire to do this by providing relevant facts, along with our perspective on the issue at hand.
Disclaimer: Views expressed herein are based on information available in publicly accessible media, involve known and unknown risks and uncertainties that could cause actual results, performance, or events to differ materially from those expressed or implied herein. The information herein is for general purposes only. Stocks/Sectors/Views referred are illustrative and should not be construed as an investment advice or a research report or a recommendation by HDFC Mutual Fund (“the Fund”) / HDFC Asset Management Company Limited (HDFC AMC) to buy or sell the stock or any other security. HDFC AMC is not indicating or guaranteeing returns on any investments. Past performance may or may not be sustained in the future and is not a guarantee of any future returns. The recipient(s), before taking any decision, should make their own investigation and seek appropriate professional advice.
MUTUAL FUND INVESTMENTS ARE SUBJECT TO MARKET RISKS, READ ALL SCHEME RELATED DOCUMENTS CAREFULLY.
Stay ahead with our insights
Did you find this interesting?
Your opinion matters - share your thoughts and help us improve.