- Entering text into the form field will trigger a list of options
Trending Searches
- Invest / Login

Equity valuations remain reasonable despite the market uptick!

Last Updated On: 10 Nov 2026
5 min read
What’s the Point?
- Despite the gains Indian markets saw last week, equity valuations remain reasonable relative to September 2024, which is when the broader markets peaked.
- The forward P/E ratio of the Nifty 100 stood at 18.5x vs its 10-year average of 19.3x. For the Nifty Midcap 100 Index, the forward P/E ratio stood at 22.8x vs. 10-year average of 23.2x, and the forward P/E for BSE Smallcap 250 Index was 21.9x vs. its 10-year average of 18.7x (as of Nov 6, 2026).
- The normalization of valuations is broad-based: far more stocks now trade below 30x forward earnings, and 5 of 12 sectors trade below their own 10-year average, compared with just 1 in September 2024.
- With valuations close to or below long-term averages, investors can potentially continue to accumulate equity mutual funds, especially through SIPs.
Index Level: The Premia of 2024 have Largely Unwound
When the broad markets peaked in September 2024, large, mid and smallcap index valuations were all priced well above their 10-year averages. Midcaps and smallcaps in particular had steep valuation premia at that time, with their valuations nearly three standard deviations (SD) above the historical 10-year average. Since then, valuations of all 3 indices have come closer to their long-term averages.
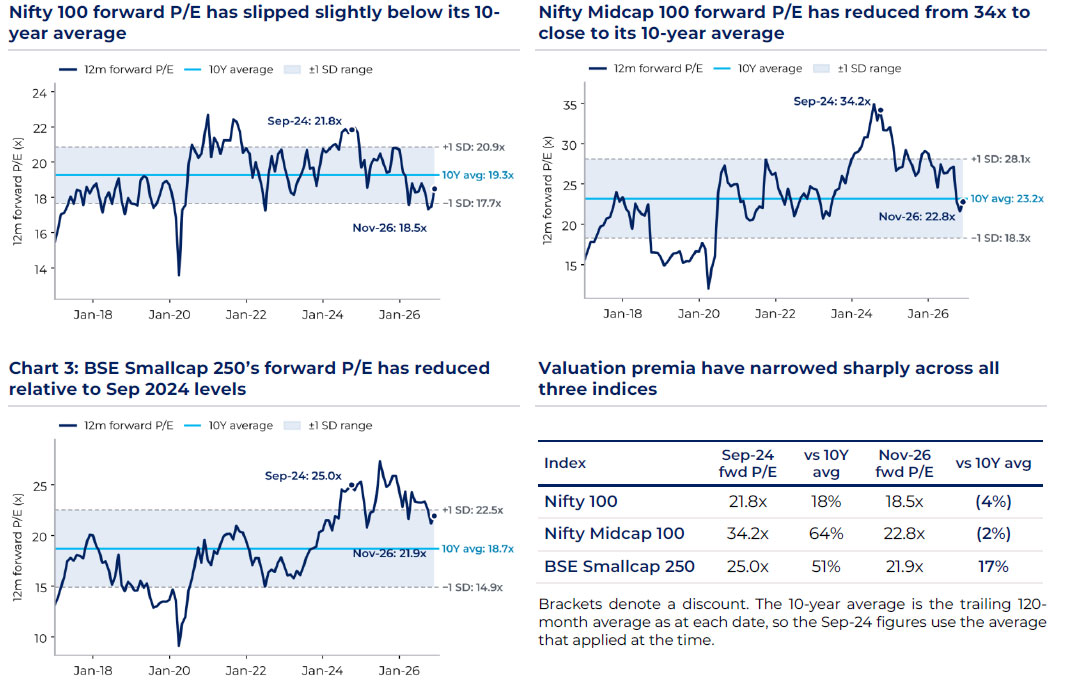
Source: Bloomberg, Kotak Institutional Equities, HDFC MF calculations. Data as of Nov 6, 2026. 10-year average and SD are calculated over the trailing 120 months.
Stock Level: Fewer stocks within indices command premium valuations
Index multiples can hide what is happening underneath. Grouping each index’s stocks by their forward P/E shows that the valuation multiple compression is broad-based, not driven by a few large companies.
41% Nov 2026 | Midcap stocks below 30x: 41% of Nifty Midcap 150 stocks now trade below 30x forward P/E, up from 25% in Sep-24. The share above 60x has fallen from 24% to 10%. |
58% Nov 2026 | Smallcap stocks below 30x: 58% of BSE Smallcap 250 stocks now trade below 30x, up from 41% in Sep-24, and the share above 40x has fallen from 43% to 26%. About 13% still trade above 60x, so stock selection remains important. |
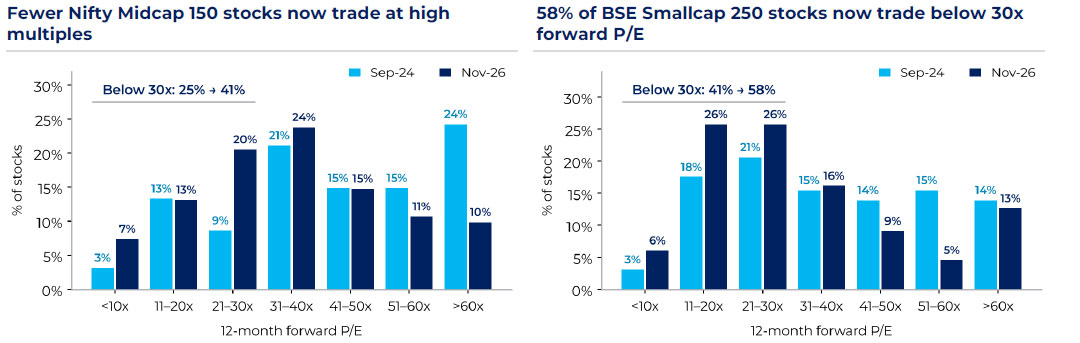
Source: Bloomberg, Kotak Institutional Equities. Data as of Nov 6, 2026.
Sector Level: Sector premia have broadly narrowed since September 2024
In September 2024, 11 of the 12 sectors tracked traded above their own 10-year average, led by utilities (+88%), cement (+50%), IT services (+33%) and pharma (+32%). Today, 5 of 12 trade below it:
- Deepest discounts: IT services (−22%), private banks (−20%), consumer ex-ITC (−19%) and tobacco (−15%). Private banks, at 2.0x forward book value, remain in the lower part of their 10-year range.
- Near average: Near average: metals (−5%), consumer discretionary (+2%), oil & gas (+3%) and autos (+1%). These sectors traded at premia of 18–30% in Sep-24.
- Still at a premium: pharma (+24%), utilities (+11%), cement (+19%) and PSU banks (+9%), though utilities and cement valuations have recently corrected considerably relative to September 2024 levels.
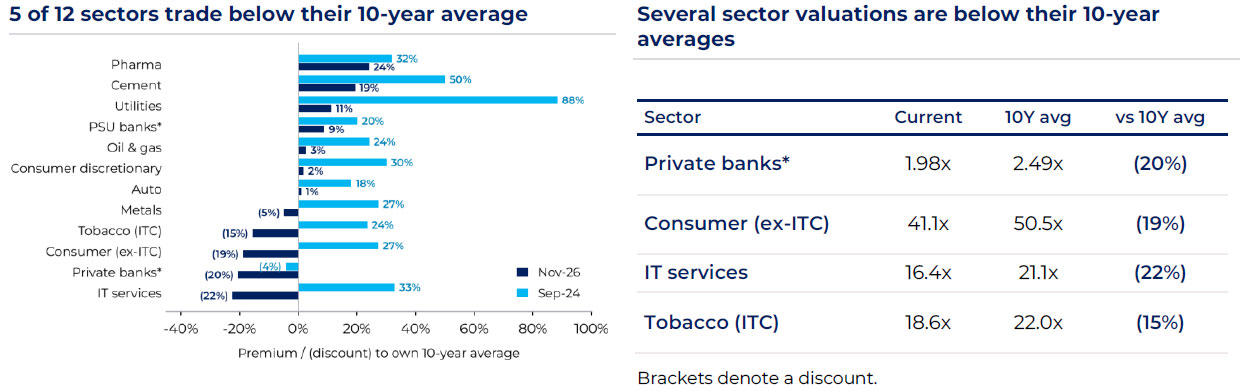
Source: Kotak Institutional Equities. Data as of September 30, 2024 and November 6, 2026. *Banks on 12-month forward P/B; all other sectors on 12-month forward P/E.
Conclusion
Across index, stock and sector levels, the message is consistent: the valuation excesses of September 2024 have largely been worked off. Largecaps and midcaps now trade close to their 10-year forward P/E averages and smallcap valuations remain moderately above average. Several sectors trade at a discount to their history, and the share of very expensive stocks has fallen significantly across midcaps and smallcaps.
While valuations do not predict short-term market moves, starting valuations tend to influence returns going ahead. In light of this, today’s starting point is far more comfortable than it was two years ago. This could potentially be an opportune time to accumulate equity mutual funds, especially through SIPs, which could help average out short-term volatility.
Sources: Kotak Institutional Equities, Bloomberg, HDFC MF calculations.
About Tuesday’s Talking Point (TTP):
TTP is an effort by HDFC AMC to guide key conversations in the Indian financial markets and investing ecosystem. We aspire to do this by providing relevant facts, along with our perspective on the issue at hand. Please provide your feedback at this link: https://forms.office.com/r/Cr8JNjMGWk
Disclaimer: Views expressed herein are based on information available in publicly accessible media, involve known and unknown risks and uncertainties that could cause actual results, performance, or events to differ materially from those expressed or implied herein. The information herein is for general purposes only. Stocks/Sectors/Views referred are illustrative and should not be construed as an investment advice or a research report or a recommendation by HDFC Mutual Fund (“the Fund”) / HDFC Asset Management Company Limited (HDFC AMC) to buy or sell the stock or any other security. HDFC AMC is not indicating or guaranteeing returns on any investments. Past performance may or may not be sustained in the future and is not a guarantee of any future returns. The recipient(s), before taking any decision, should make their own investigation and seek appropriate professional advice.
MUTUAL FUND INVESTMENTS ARE SUBJECT TO MARKET RISKS, READ ALL SCHEME RELATED DOCUMENTS CAREFULLY.
Stay ahead with our insights
Did you find this interesting?
Your opinion matters - share your thoughts and help us improve.